Do we qualify for Nebraska’s first-time buyer program?
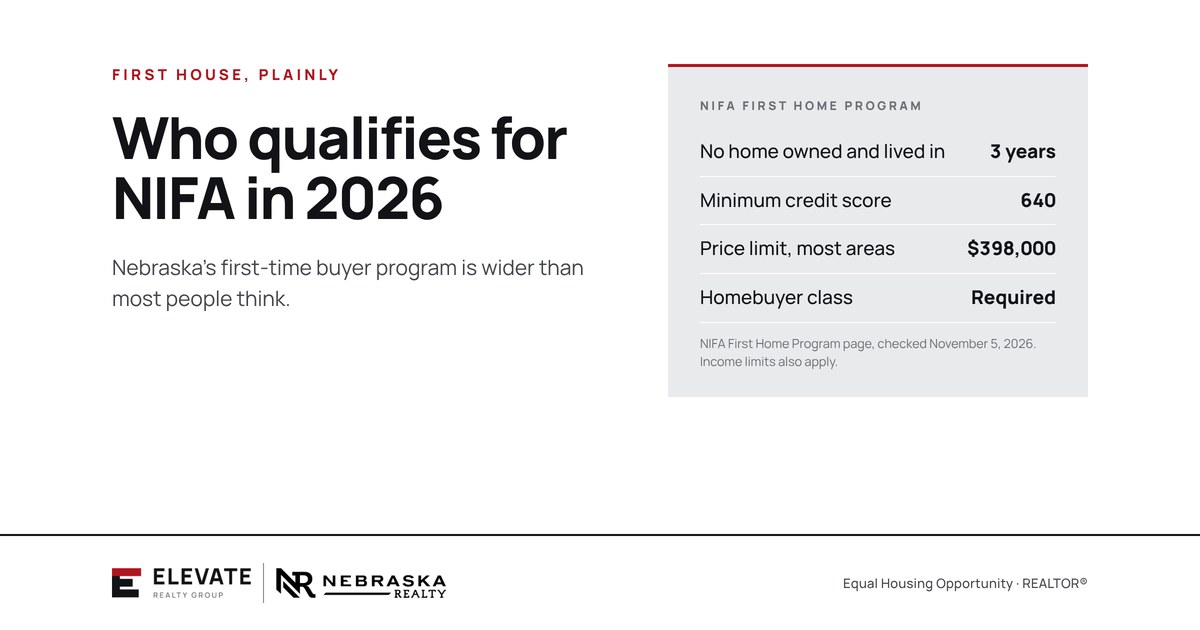
You may qualify for the Nebraska Investment Finance Authority (NIFA) First Home Program if you haven’t owned and lived in a home in the last 3 years, your credit score is at least 640 and the home is under the price limit, which is $398,000 for a single-unit home in most areas. Income limits also apply, and you’ll need to finish a homebuyer education class before closing. A NIFA-participating lender can check your numbers.
Ten minutes with a NIFA-participating lender can tell you whether you qualify.
By Cassi Ohlin | November 9, 2026
When a young couple tells me they “probably don’t qualify for anything,” I ask them to hold that thought for ten minutes. NIFA’s program is wider than most people expect, and it’s built for exactly the buyers who think it isn’t for them.
Here’s what the NIFA First Home Program page lists as the main requirements.
Who counts as a first-time buyer
For NIFA, a first-time buyer is someone who hasn’t owned and lived in a primary residence in the past 3 years. So if you owned a home years ago, you may still qualify.
There are exceptions too. Qualified veterans and buyers purchasing in NIFA target areas may not need to meet the 3-year rule, and NIFA can make case-by-case exceptions for people who lost a home through divorce, a natural disaster or a forced job move.
The credit and budget requirements
- Credit score: at least 640.
- Debt-to-income ratio (DTI): your total monthly debt payments, including the new house payment, can be up to 45% of your gross monthly income, or 50% with a credit score of 660 or higher.
- Homebuyer education: first-time buyers need to complete a NIFA-approved class before closing.
These are NIFA’s program limits. Your lender and loan type can set stricter rules, so treat them as the outer edge, not a target. A payment that fits your life matters more than the most you can be approved for. Here’s how we think about the real monthly payment.
Price and income limits
As of July 13, 2026, NIFA’s purchase price limit for a single-unit home is $398,000 in most areas and $485,500 in NIFA target areas. Whether a home is in a target area depends on its census tract, so ask your lender to check the address.
Household income limits are separate. They vary by county and household size, so look them up on NIFA’s program page or ask your lender rather than guessing.
Help with the down payment
NIFA also offers a Homebuyer Assistance option that pairs the first mortgage with a second loan. Terms and rates change, so check NIFA’s interest rates page for the current numbers and ask your lender how it would work for you.
Because it’s a loan, not a grant, it shows up in your monthly budget. That’s not a reason to skip it. It’s a reason to run the full payment before you decide.
How to get started
- Check the 3-year rule, or whether an exception applies to you.
- Confirm your credit score and add up your monthly debts.
- Look up the price limit for the area and the income limit for your county and household size.
- Talk with a NIFA-participating lender and sign up for a homebuyer education class.
Frequently asked questions
What credit score do I need for NIFA?
NIFA’s First Home Program requires a minimum credit score of 640. Some lenders and loan types require more, so check with a NIFA-participating lender.
What is NIFA’s purchase price limit in 2026?
As of July 13, 2026, the limit for a single-unit home is $398,000 in most areas and $485,500 in NIFA target areas. Target areas are set by census tract.
Can I use NIFA if I owned a home before?
Possibly. NIFA counts you as a first-time buyer if you haven’t owned and lived in a primary residence in the past 3 years. Qualified veterans and buyers in target areas may be exempt from that rule.
Do I have to take a homebuyer class for NIFA?
Yes. First-time buyers using the First Home Program need to complete a NIFA-approved homebuyer education class before closing.
Ten minutes is worth it
If you’ve been assuming you don’t qualify, check before you decide. I’m happy to sit down with you and a NIFA-participating lender and look at your real numbers. Reach out anytime at 402-728-8750 or [email protected].
About Cassi Ohlin
REALTOR® and Team Lead at Elevate Realty Group, brokered by Nebraska Realty. Leads with warmth: makes you feel like the only person in the room. Milford-based, serves the same Lincoln-area communities.
Source: NIFA First Home Program, checked November 5, 2026.