Why is homeowners insurance so expensive in Nebraska?
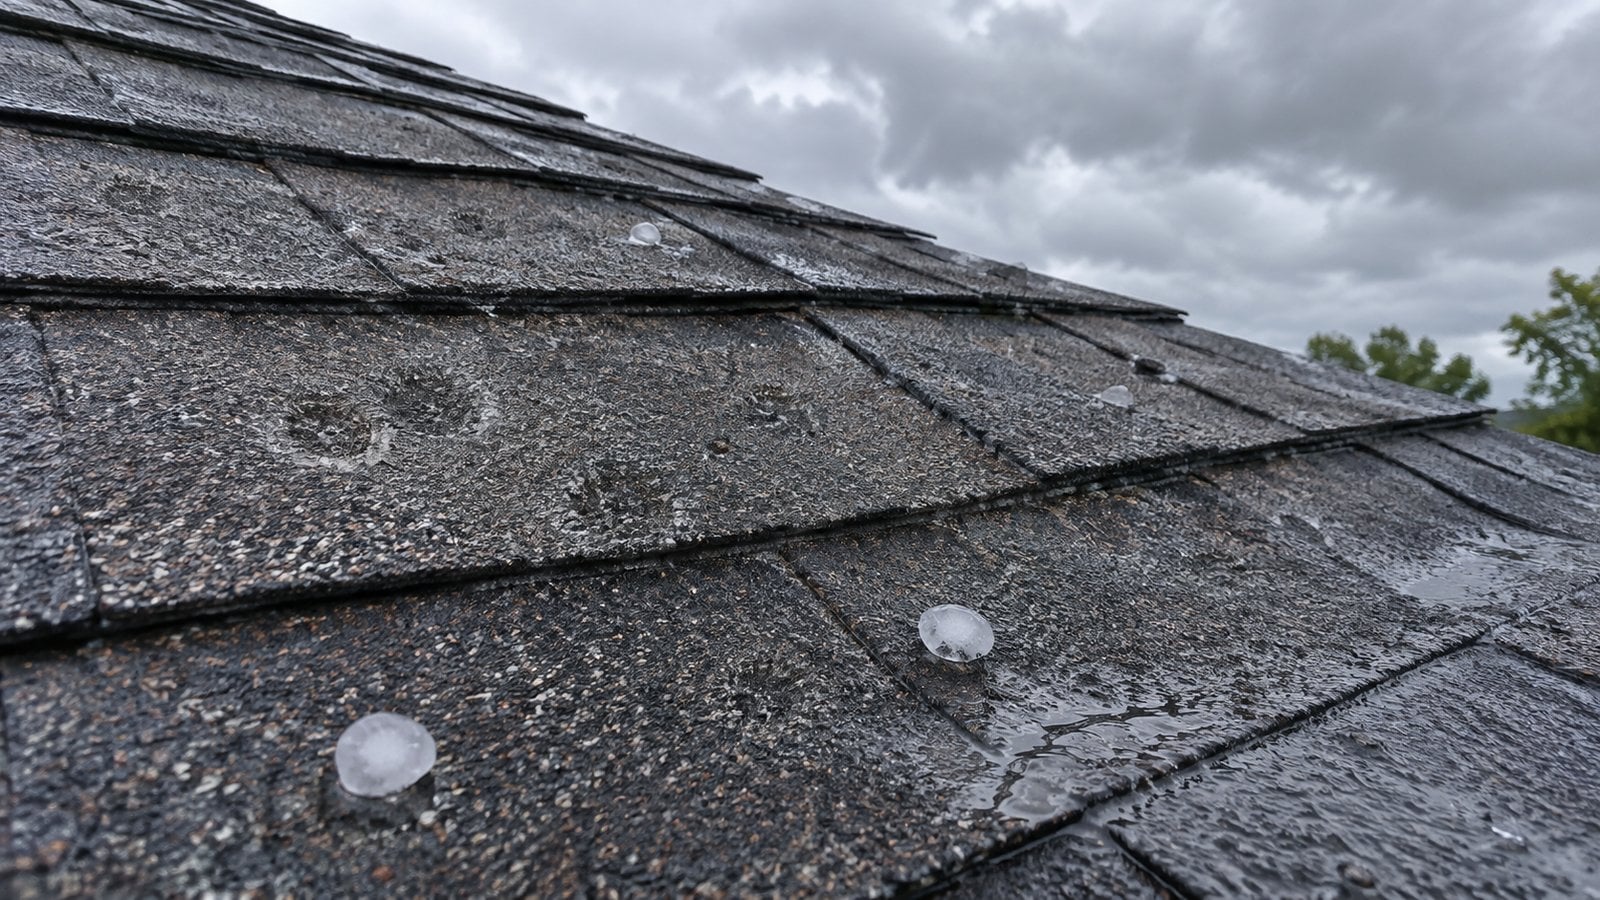
Hail and wind storms are a big part of the risk insurers price in across Nebraska, so a home’s roof age and type have a large effect on your premium. Some policies pay roof claims at actual cash value, which subtracts for age, and storm deductibles can be a percentage of the home’s insured value instead of a flat dollar amount. Get a quote on the specific house during your inspection period, before you’re locked in.
By Jorin Masley | November 12, 2026
Insurance is the line on the payment estimate that surprises buyers the most. Two houses at the same price can come back with very different quotes, and the reason is usually sitting on top of the house.
What drives your premium
- The roof. Age, material and condition matter more than almost anything else in a hail state. An older roof can mean a higher premium or less generous roof coverage.
- Your deductible. A higher deductible lowers your premium, but only choose one you could actually pay after a storm.
- How the policy pays. Replacement cost and actual cash value coverage price differently (more on that below).
- The home’s claims history. Insurers may look at past claims on the address. Ask the seller what was filed.
Replacement cost vs. actual cash value
The Nebraska Department of Insurance’s homeowners guide explains the difference plainly. Replacement cost coverage pays to repair or rebuild with similar materials. Actual cash value subtracts for age and wear, and usually doesn’t pay enough to fully repair the damage.
On a newer roof, the gap may be small. On an older roof after a hailstorm, it can be the difference between a new roof and a big check you write yourself. Ask which one applies to your roof before you buy.
Percentage deductibles
The same guide notes that catastrophe deductibles, such as for wind or hail, can be a percentage of your coverage instead of a flat dollar amount. For example, a 1% deductible on a home insured for $250,000 is $2,500 before insurance pays. That example is just to show the math; your policy sets the actual percentage.
What a standard policy won’t cover
- Flood. Standard homeowners policies don’t cover flood. If a home is in a federal flood hazard area and you’re using a federally backed loan, flood insurance is required. Your lender may require it in other cases too.
- Slow leaks and mold from neglect or gradual damage are generally excluded. Sudden plumbing leaks are generally covered.
- Sewer backup usually needs to be added to your policy.
Get the quote before your deadline
Your inspection period is your window to back out if something doesn’t work. Insurance belongs in that window. Ask the seller for the roof’s age and any past claims, have your inspector look closely at the roof and get a quote on that exact address.
Then add it to your real monthly payment. If the roof is near the end of its life, that’s a fair item to raise after the inspection.
Frequently asked questions
Why is home insurance higher in Nebraska?
Nebraska homes face frequent hail and wind storms, which drive roof claims. Insurers price that risk in, so roof age, roof type and your deductible have a large effect on what you pay.
What is actual cash value roof coverage?
Actual cash value pays for damage minus depreciation for age and wear. According to the Nebraska Department of Insurance, it usually doesn’t pay enough to fully repair the damage, unlike replacement cost coverage.
Does homeowners insurance cover flooding in Nebraska?
No. Standard homeowners policies don’t cover flood. Flood insurance is a separate policy, and it’s required for federally backed loans on homes in federal flood hazard areas.
When should I get an insurance quote when buying a house?
During your inspection period, on the specific address. That way you can still negotiate or walk away if the quote changes your budget.
Know the roof, know the number
Insurance doesn’t have to be a surprise at closing. If you want help getting a quote and reading the policy on a home you’re considering, I’m happy to help. Reach out anytime at 402-728-8750 or [email protected].
About Jorin Masley
REALTOR® and Team Lead at Elevate Realty Group, brokered by Nebraska Realty. Leads with clarity: makes the complicated plain and shows you the real numbers early. Serves Lincoln and the surrounding communities of Milford, Seward, Beatrice, Crete, Waverly, Hickman and Roca.
Source: Nebraska Department of Insurance, Homeowners Insurance Guide, checked November 5, 2026.